Section 179 Deduction 2026: How Business Owners Can Write Off Equipment Before December 31
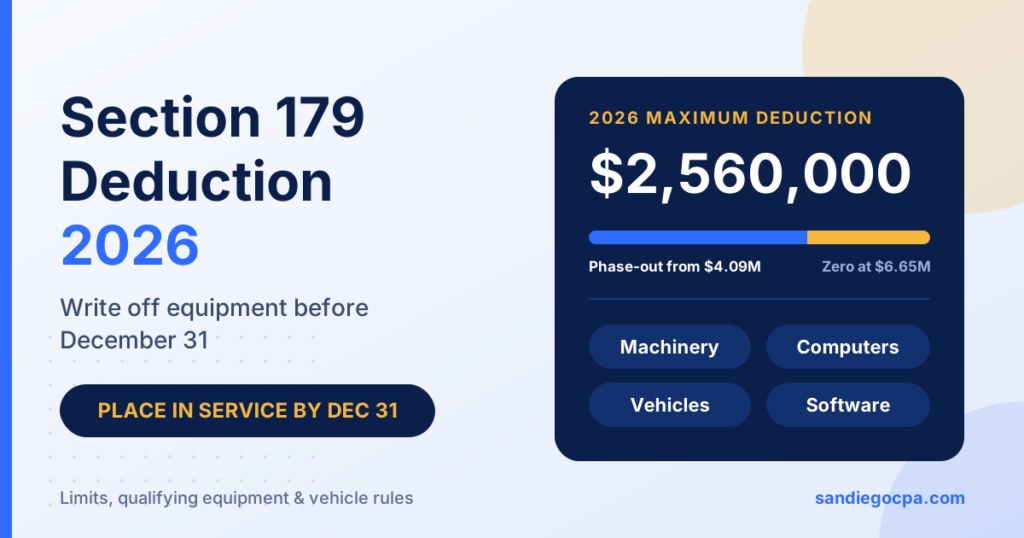
If your business needs equipment, buying it before December 31 could let you deduct the full cost on your 2026 tax return instead of spreading it over many years. That is the Section 179 deduction, and it is larger in 2026 than it has ever been. The deadline is strict, though. Equipment must be placed in service by December 31, not merely ordered. This guide covers the 2026 limits, what qualifies, how Section 179 compares with bonus depreciation, and the vehicle rules that trip up business owners. Equipment purchases are Move 15 in our year-end tax planning checklist 2026, so if you haven’t reviewed your full list of year-end moves, start there. What Is the Section 179 Deduction? Section 179 of the Internal Revenue Code lets a business elect to deduct the full purchase price of qualifying equipment and property in the year it is placed in service, instead of depreciating it over several years. The result is a lower taxable income and a smaller tax bill this year, plus more cash to reinvest. Section 179 Limits for 2026 The One Big Beautiful Bill Act raised the Section 179 base limit to $2.5 million, indexed for inflation after 2025. The IRS says the amount is reduced dollar for dollar once total qualifying purchases exceed $4 million. For 2026, the indexed figures are: 2026 Section 179 Figure Amount Maximum Deduction $2,560,000 Phase-Out Begins $4,090,000 of qualifying property placed in service Fully Phased Out $6,650,000 Heavy SUV Cap (6,001–14,000 lbs) $32,000 Most small and mid-sized businesses fall well below the phase-out, so they can deduct their full qualifying purchases. If you spend more than $4.09 million, the limit shrinks by every dollar above that threshold, and bonus depreciation can pick up the rest. What Equipment Qualifies? Property generally qualifies if it is tangible, used in an active trade or business, and used more than 50% for business. Common examples: Machinery and manufacturing equipment Computers, servers, and office equipment Furniture and fixtures Tools and diagnostic equipment Off-the-shelf software Certain business vehicles Both new and used equipment Land, buildings, and inventory do not qualify. Property you use personally more than half the time does not qualify either. The “Placed in Service” Rule This is the most common year-end mistake. Equipment must be placed in service, not merely ordered, to count for 2026. “Placed in service” means the asset is delivered, installed if needed, and ready and available for its intended use. A realistic timeline: Early November: Place the order, because supply chains and installation take time. Late November to mid-December: Delivery, setup, and testing. By December 31: The equipment is in use, and you keep the paperwork (invoice, delivery receipt, and installation date). Ordering a machine on December 28 that arrives in January earns no 2026 deduction. Section 179 vs. Bonus Depreciation Both let you write off equipment quickly, but they work differently. Feature Section 179 Bonus Depreciation 2026 Rate or Limit Up to $2,560,000 100% Applies To Asset-by-asset election Automatic unless you opt out Income Limit Cannot exceed business taxable income No income limitation Can Create a Loss No Yes Phase-Out Begins at $4,090,000 None Carryforward Disallowed amounts carry forward Not applicable The One Big Beautiful Bill Act made 100% first-year bonus depreciation permanent for qualified property acquired after January 19, 2025. In practice, many businesses use Section 179 first, then let bonus depreciation absorb what remains. Which should you use? Profitable business with moderate purchases: Section 179 gives you precise control over which assets to expense. Loss year, or a deduction larger than your income: Bonus depreciation can create or increase a loss. Section 179 cannot. Purchases above $4.09 million: Rely on bonus depreciation as Section 179 phases out. Business Vehicle Rules Vehicle weight (gross vehicle weight rating, or GVWR) decides how much you can deduct in year one. Vehicle Type 2026 First-Year Treatment Cars and Light Trucks (6,000 lbs or Less) Luxury-auto limits apply: $20,300 with bonus depreciation, $12,300 without. Heavy SUVs (6,001–14,000 lbs) Section 179 capped at $32,000, with 100% bonus depreciation available on the remaining cost. Trucks with Beds of 6+ Feet and Vans Seating 10+ Generally exempt from the SUV cap. Vehicles Over 14,000 lbs Not subject to the SUV cap (commercial treatment). Example: A $90,000 SUV rated at 7,200 lbs GVWR, used 100% for business and placed in service in 2026, produces a $32,000 Section 179 deduction plus $58,000 of bonus depreciation, for a $90,000 first-year total. A passenger car under 6,000 lbs with the same price is limited to the luxury auto cap, a small fraction of the cost. Business use must exceed 50%, and personal use reduces the deductible amount. Keep a mileage log. The Business Income Limit Section 179 cannot exceed your net business income for the year. For instance, a sole proprietor with $18,000 of net business income who buys a $75,000 heavy SUV can deduct only $18,000 under Section 179 this year, because the income limit applies on top of the $32,000 SUV cap. Disallowed amounts can carry forward, and bonus depreciation may help in a low-income year. Discuss this with your CPA before buying. Who Benefits Most? Sole proprietors and single-member LLCs: Claim it on Form 4562 with Schedule C. S corporations and partnerships: The deduction passes through to owners, subject to limits at the owner level. C corporations: Eligible as well. Contractors, manufacturers, medical and dental practices, restaurants, trucking, and eCommerce businesses: Often have the most equipment to buy. State Tax Differences Some states, including California, do not fully follow the federal Section 179 and bonus depreciation rules. You may get a smaller deduction on your state return, which means keeping two sets of depreciation records. Ask your CPA how your state treats the purchase before you buy. Common Section 179 Mistakes Ordering without placing in service by December 31. Overestimating vehicle deductions. Check GVWR on the door-jamb label before assuming the SUV rules apply. Ignoring the business income limit. Buying only for the deduction. A deduction saves a